A flat in Zone 1 can lose more value in real terms over five years than most buyers realise, even while the rest of Britain edges upward. That is the uncomfortable truth behind Connells Group's new forecast, published this week, and it sets up a tense winter for anyone weighing up a London purchase or sale right now.
On 2 November 2026, Connells Group released its latest house price outlook, and on 4 November 2026 the implications are already rippling through London's buying and selling decisions. With the Bank of England's rate decision landing on Thursday 5 November 2026, this is a pivotal week for anyone about to commission a RICS survey or valuation.
Key Takeaways
- Connells forecasts London house prices falling 1% in 2026, with growth of 2% returning in 2027.
- Inner London is the weak spot: minus 4.5% in 2026 and only plus 0.5% in 2027, against Outer London's minus 0.5% then plus 3%.
- Mortgage rates rose from 4.14% to 5.22% in 2026, pushing a typical monthly repayment to £1,224.
- The Bank of England is widely expected to raise Bank Rate to 4% on 5 November 2026.
- With prices still falling in parts of London, independent valuation evidence matters more than ever for negotiating and avoiding down-valuations.
What Connells Is Forecasting for the London House Price Outlook 2027
Research director Aneisha Beveridge says: "The pick-up in home moves many expected this year hasn't materialised." Connells' regional breakdown shows a clear divide within London itself.
| Area | 2026 | 2027 |
|---|---|---|
| Great Britain | +1% | +1.5% |
| London overall | -1% | +2% |
| Outer London | -0.5% | +3% |
| Inner London | -4.5% | +0.5% |
| South East | 0% | +1% |
Beveridge adds: "We expect house price growth to build in 2027 and 2028," and notes "London should return to growth, particularly in Outer London." For context on broader regional divergence, see our coverage of valuation accuracy amid regional price divergence.
Why Inner London Is Lagging Behind in This Valuation Picture
Inner London's forecast minus 4.5% in 2026 stands out sharply against a GB average of plus 1%. Connells points to two drivers behind this gap: higher property taxes on higher-value homes, and weaker international investor demand that previously underpinned central London pricing.
The real-terms picture is starker still. Over the last five years, consumer prices rose 21.8% while London house prices rose just 0.9%, compared with 10.9% for Great Britain overall. In effect, London property has fallen substantially in real purchasing power, even before accounting for this year's nominal falls. This mirrors trends covered in our piece on valuation adjustments for London's price cooling.
Mortgage Rates and Thursday's Bank of England Decision
Connells estimates that higher-than-expected mortgage rates removed around 100,000 transactions from its original 2026 forecast. The average mortgage rate paid by buyers climbed from 4.14% at the start of 2026 to 5.22% in October. A typical monthly repayment on a 75% LTV, 25-year mortgage is now £1,224, up from £1,115 a year ago and £874 in 2019.
Beveridge warns: "But if rates remain around 5%, the risk of small house price falls in 2027, rather than growth, increases significantly."
The Bank of England held Bank Rate at 3.75% on 17 September 2026, but the Monetary Policy Committee meets on Thursday 5 November 2026, and a quarter-point rise to 4% is widely expected, with 54 of 63 economists in a Reuters poll forecasting the move, following CPI inflation rising to 3.5% in September. ONS data already shows UK average prices rose just 0.8% year-on-year in August 2026, down from 1.9% a year earlier. See our recent analysis of mortgage approvals falling to their lowest since December 2023 for the lending backdrop.
What the Connells London House Price Forecast 2027 Means for Buyers
If you are buying in a falling or flat market, valuation evidence is your strongest negotiating tool. Three practical points stand out:
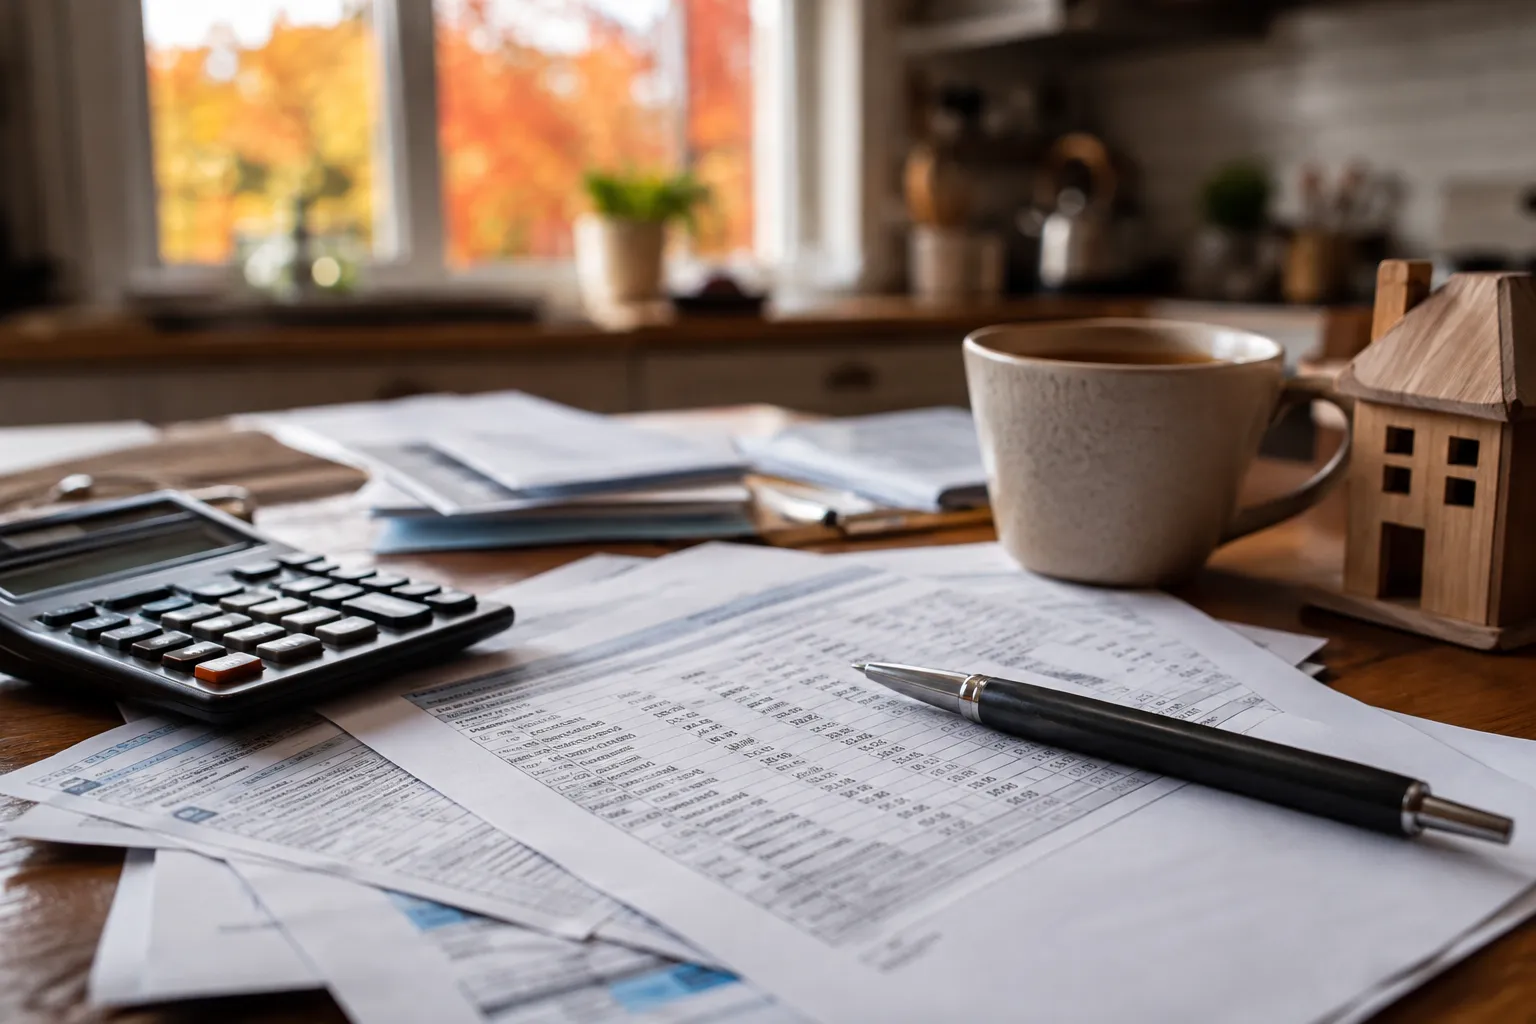
- Level 2 vs Level 3 surveys: A Level 2 Homebuyer Report suits standard, reasonably modern flats and houses in apparent good condition. A Level 3 Building Survey is advisable for period Inner London properties, conversions, or anything showing signs of disrepair, giving you detailed evidence to renegotiate.
- Independent RICS valuation vs lender valuation: Lender valuations are brief and conservative, often designed to protect the mortgage rather than help you negotiate. An independent valuation from a RICS-regulated firm like Prince Surveyors gives a fuller, evidence-based figure you can use with agents and sellers.
- Down-valuation risk: When prices are falling, as in Inner London, lenders become more cautious and down-valuations more common. Commissioning your own survey early helps you anticipate and challenge any mismatch. Our guide on how to negotiate a house price down after a survey explains the process in detail.
What This Means for Sellers and Flat Owners
Sellers in Inner London need to price with the minus 4.5% backdrop firmly in mind, not last year's asking prices. A pre-sale survey can flag defects before buyers do, preventing late renegotiation. Flat owners should also be alert to leasehold complications that can affect valuation, covered in our article on leasehold reform and what London flat owners should do this November, and our techniques for valuing flats when price growth stalls.
Relisting after a failed sale carries its own risks, as explored in our review of why one in four relisted sellers already failed once.
What to Do This Week
- Check how Thursday's Bank of England decision affects your mortgage offer or remortgage plans.
- If buying in Inner London, commission an independent RICS valuation before agreeing a final price.
- If selling, get a realistic, evidence-based asking price rather than relying on outdated comparables.
- Book a Level 2 or Level 3 survey early to build negotiating leverage before exchange.
- Review leasehold terms if you own or are buying a flat.
FAQ
Will London house prices fall further in 2027?
Connells forecasts overall London growth of 2% in 2027, but Inner London is expected to rise only 0.5%, and Beveridge warns that persistent 5% mortgage rates could tip this into small falls instead.
Why is Inner London falling more than Outer London?
Connells attributes this to higher property taxes on higher-value homes and weaker international investor demand, while Outer London benefits from stronger owner-occupier demand.
Should I get an independent valuation if I'm buying in London now?
Yes. In a falling or uncertain market, an independent RICS valuation gives you evidence to negotiate and helps you anticipate lender down-valuations.
What survey should I choose for a London flat?
A Level 2 Homebuyer Report suits modern flats in good condition; a Level 3 Building Survey is recommended for older conversions or properties with visible defects.
Conclusion
This week's Connells forecast confirms what many Inner London owners already sense: values have fallen in real terms for years, and 2026 brings a further nominal dip before modest 2027 recovery. With mortgage rates still elevated and a Bank of England decision due Thursday, both buyers and sellers need solid, independent evidence rather than guesswork. Prince Surveyors, a London RICS-regulated firm, offers Level 2 and Level 3 surveys, independent valuations and party wall services to help you transact with confidence this winter. Book a survey or valuation today to make sure your next move is backed by proper evidence.